With South Africa’s digital lending and fintech market value reaching USD 980 million in 2026, the opportunity for growth is immense, yet many providers remain tethered to the past. Even with the repo rate holding steady at 7.00%, the pressure to maintain margins whilst managing manual, paper-heavy credit approvals is becoming unsustainable. If you’re struggling to balance high operational costs with the complexities of NCR and POPIA compliance, you’ve likely felt the need for a more agile approach. Implementing a robust digital lending platform south africa requires more than just a technical upgrade; it’s about building a strategic engine that can navigate our unique credit landscape.
We believe that scaling a financial service should be a collaborative journey rooted in reliability and precision. This strategic guide will show you how to modernise your credit operations and scale using cutting-edge technology designed for the local market. You’ll learn how to achieve faster loan processing times through automated risk assessment and establish a scalable digital infrastructure that ensures long-term stability. We will walk through the essential steps to move from a broad vision to concrete execution, ensuring your business remains a stable anchor in a rapidly changing technological environment.
Key Takeaways
Understand how modernising your credit operations through cloud-native architectures facilitates sustainable growth and reduces operational overhead.
Identify the core features of a modern digital lending platform south africa, focusing on how AI-driven scoring and secure disbursements accelerate turnaround times.
Evaluate the strategic advantages of custom software development to protect your proprietary IP and avoid the limitations of generic lending tools.
Navigate the latest NCR and POPIA requirements with precision to ensure your digital infrastructure remains secure and compliant in 2026.
Explore a structured path from strategic consulting to cloud deployment, positioning your financial services as a stable anchor in a changing market.
What is a Digital Lending Platform and Why Does it Matter in 2026?
Understanding What is a Digital Lending Platform starts with recognising it as an end-to-end software solution that automates the entire loan lifecycle. In 2026, these systems have evolved far beyond basic data entry tools. They now function as sophisticated engines that manage everything from initial customer onboarding and credit vetting to disbursement and collections. For any financial institution, a digital lending platform south africa is the cornerstone of a modernised service, replacing slow, fragmented legacy systems with a unified, cloud-native architecture.
To better understand how these tools are reshaping the local market, watch this helpful video:
The transition from legacy credit systems to AI-driven architectures is fueled by a need for absolute precision and speed. Traditional methods often result in bottlenecks that frustrate borrowers and increase risk for lenders. Modern platforms utilise AI & data automation to ingest vast amounts of data instantly, ensuring that credit decisions are based on real-time insights rather than outdated snapshots. This shift allows lenders to remain agile whilst maintaining a high standard of reliability.
South African businesses are currently prioritising digital transformation to drastically reduce “time-to-cash”. In a competitive market, the ability to put capital into a borrower’s hands within minutes rather than days is a significant advantage. Mobile-first interfaces play a vital role here, especially in reaching the unbanked and underbanked national population. By providing access to financial services through the devices people already carry, these platforms foster greater financial inclusion across the country.
The Evolution of Credit in South Africa
Credit management has moved from manual, subjective vetting to real-time algorithmic risk assessment. This evolution relies on robust cloud application services to ensure maximum platform uptime and accessibility. By removing physical barriers and geographical constraints, digital platforms democratise access to capital. This means an entrepreneur in a remote area can secure funding with the same ease and speed as a business based in a major urban centre like Johannesburg or Cape Town.
Core Benefits for Financial Institutions
Adopting automated workflows leads to a substantial reduction in operational overheads. By removing the need for manual intervention at every stage, institutions can process significantly higher loan volumes without a linear increase in staff costs. Precision also improves; algorithmic scoring reduces the human error inherent in traditional vetting, leading to a healthier loan book. For South African SMEs, the ROI of a Loan Management System is found in the ability to secure working capital at the exact moment of opportunity, turning credit into a catalyst for immediate and sustainable expansion.
Essential Features of a Modern Digital Lending Platform
Selecting the right components for your digital lending platform south africa is a strategic decision that determines your long-term scalability. Whilst many off-the-shelf products offer basic functionality, a truly robust system must handle the specific nuances of the local credit market. You need a platform that doesn’t just record data but actively works to protect your margins and improve the user journey. These core capabilities form the foundation of a reliable system:
Automated Credit Scoring: Integrating AI and data automation to process applications in seconds rather than days.
Secure Digital Wallets: Facilitating seamless disbursements and repayments through integrated payment gateways.
Interactive Dashboards: Providing real-time analytics for lenders to monitor portfolio health and for borrowers to manage their accounts.
Multi-Channel Support: Ensuring accessibility via web, mobile, and USSD to reach the widest possible national audience.
AI-Driven Risk Assessment and Automation
Incorporating AI automation solutions allows your platform to predict default patterns with far greater precision than traditional credit scores. This isn’t just about speed; it’s about accuracy. By automating KYC (Know Your Customer) and AML (Anti-Money Laundering) checks, you reduce manual friction whilst ensuring rigorous compliance. We’ve found that custom-built algorithms often outperform generic global models. Localised data reflects South African spending habits and financial behaviours more accurately, which leads to a more stable and predictable loan book.
User Experience and Interface Design
Borrower retention is heavily influenced by the ease of the initial digital journey. Professional UI/UX design services are critical for simplifying complex application forms into intuitive, bite-sized steps. In the South African context, high performance on low-bandwidth mobile connections is a non-negotiable requirement. A platform that fails to load on a basic smartphone in a rural area isn’t truly accessible. By focusing on lightweight yet powerful interfaces, you ensure that your service remains available to everyone, regardless of their device or location.
If you’re looking to refine these features for your specific business model, our team can help you customise your lending infrastructure for long-term success. We believe that technology should be a supportive partner in your growth, providing the steady confidence you need to scale your financial services with precision.
Custom Development vs. Off-the-Shelf Lending Software
Deciding whether to build a bespoke solution or license a generic product is a pivotal moment for your business strategy. Whilst off-the-shelf software offers a faster entry point, it often introduces the risk of “vendor lock-in”, where your growth is constrained by another company’s roadmap. For a digital lending platform south africa, owning your proprietary IP isn’t just a technical preference; it’s a significant asset that increases the valuation of your financial institution. Custom engineering allows you to architect unique credit products that align perfectly with local market needs, such as specific repayment structures or interest rate tiers that generic SaaS tools simply cannot accommodate.
We believe that technology should serve your vision, not limit it. Choosing custom software development enables you to build a system that reflects your specific risk appetite and operational style. Whilst the initial capital expenditure for custom builds is higher than a monthly subscription, the long-term operational savings are substantial. You eliminate recurring per-user fees and gain the freedom to scale without penalty, turning your technology stack into a stable anchor for future expansion.
When to Choose a Custom Solution
Bespoke development is the right path when your product requirements involve complexities that standard tools ignore. If you need deep, seamless integration with local credit bureaux like Experian or TransUnion, or direct links into the South African banking grid, a custom approach is often essential. This path is also vital if you aim to build a unique brand experience that stands out amongst a sea of generic competitors. A custom-built Loan Management System ensures that every touchpoint, from the application to the final repayment, feels modern and precise.
The Role of Staff Augmentation in Development
Bridging the local developer talent gap is one of the biggest challenges in fintech today. Many institutions find that staff augmentation provides the necessary momentum to meet aggressive launch deadlines without the overhead of permanent hiring. By integrating dedicated software engineering experts into your existing team, you ensure project continuity and maintain high standards of precision. This model allows you to scale your technical capacity quickly, bringing in specialised skills for cloud deployment or AI integration exactly when they’re needed most. It’s a practical way to maintain the “quiet confidence” required to execute a complex digital transformation whilst keeping your core focus on financial service delivery.
Navigating Compliance and Security in South Africa
Operating a digital lending platform south africa involves more than just processing applications; it requires a deep commitment to the regulatory frameworks that protect both the lender and the borrower. In 2026, the South African Reserve Bank and the National Credit Regulator (NCR) have set high standards for digital transparency. Reliability in this sector is built on a foundation of methodical execution and strict adherence to the National Credit Act. By integrating compliance directly into your software architecture, you transform a potential hurdle into a competitive advantage that inspires trust.
Manual reporting is often the primary cause of friction in growing financial institutions. A modern platform should automate the generation of Form 39 and Form 40 reports, ensuring that your data is always ready for submission. Managing reckless lending checks within the digital workflow is equally critical. By using algorithmic affordability assessments, you can ensure every loan meets the legal requirements for consumer protection whilst maintaining your operational speed. Integrating with the South African Fraud Prevention Service (SAFPS) adds an extra layer of security, allowing you to flag suspicious activity before it impacts your bottom line.
NCR and National Credit Act Compliance
With the Conduct of Financial Institutions (COFI) Bill now creating a unified framework for open finance, your platform must be agile enough to adapt to these shifting rules. Ensuring your interest rate calculations remain within the National Credit Act caps, such as the 5% per month limit for short-term consumer loans, must be an automated function of your core system. This precision prevents accidental overcharging and protects your organisation from regulatory scrutiny. Automated workflows also ensure that every borrower receives the required pre-agreement statements and quotations, honouring the transparency standards expected in a modern financial market.
Data Privacy and POPIA
Protecting your infrastructure requires more than basic firewalls. Utilising robust cloud solutions provides the high-end security and encryption needed to defend against sophisticated cyber threats. Data privacy is a cornerstone of modern financial services, and implementing POPIA-compliant protocols ensures that borrower information is handled with the precision it deserves. This includes securing data with advanced encryption and managing strict access controls so that only authorised personnel can view sensitive files. Your platform must also provide clear mechanisms for managing consent and data subject rights, allowing borrowers to see exactly how their information is used. Non-compliance in the South African financial sector can result in administrative fines of up to R10 million or criminal prosecution for significant data breaches.
How Mkhaya MK Modernises Lending with Custom Engineering
At Mkhaya MK, we understand that a digital lending platform south africa is more than just code; it is the lifeblood of your financial service. Our proprietary Loan Management System serves as a robust foundation, designed specifically to handle the intricacies of the local market whilst providing the flexibility to scale. We don’t just provide a tool; we embark on a collaborative journey with you, moving methodically from strategic consulting through to complex cloud deployment. This end-to-end process ensures that every architectural decision aligns with your long-term business goals and operational needs.
By leveraging AI & data automation, we help you create smarter credit operations that learn and adapt to borrower behaviour. This precision-focused approach reduces human error and enhances the reliability of your risk assessments. We believe in a partnership model where your success is our primary metric, providing a stable anchor in a technological landscape that never stops moving. Our goal is to inspire trust through transparency and methodical execution, ensuring your platform remains a visionary leader in the fintech space.
Bespoke Software Engineering for Fintechs
Designing scalable architectures is at the heart of our service offering. As your loan book grows, your infrastructure must remain agile and responsive to avoid the bottlenecks associated with legacy systems. Our software engineering teams focus on integrating your platform with local payment gateways and the broader financial ecosystem, ensuring seamless transactions for your customers. Our digital transformation methodology is built on commitment and integrity, allowing us to refine your processes whilst building for future innovation without the constraints of generic software.
Partnering for National Success
Success in the South African fintech space requires access to high-level expertise that can be difficult to source locally. Our staff augmentation model allows you to tap into top-tier technical professionals who become a dedicated extension of your own team. This approach ensures you have the talent needed to maintain your digital lending platform south africa at the cutting edge of the industry. We provide continuous support and optimisation, ensuring your system remains secure and efficient long after the initial launch. Take the next step toward modernising your credit operations; we invite you to consult with our engineering experts today to discover how we can build a more stable and successful future together.
Building the Future of South African Credit
Transitioning to a modernised credit operation is a strategic move that requires both vision and precision. We’ve explored how a digital lending platform south africa can transform manual bottlenecks into automated engines of growth, whilst ensuring your business remains compliant with NCR and POPIA regulations. By choosing custom engineering over generic software, you secure your proprietary IP and build a system that truly reflects your unique brand identity. Success in 2026 isn’t just about fast processing; it’s about creating a stable, scalable foundation that inspires long-term trust amongst your borrowers.
Our team is ready to support your journey with our specialised Loan Management System (LMS) and deep expertise in South African financial compliance. We combine scalable AI and cloud engineering capabilities to ensure your infrastructure is as agile as the market demands. We invite you to discuss your digital lending vision with Mkhaya MK and discover how a dedicated partnership can turn your strategic goals into a concrete reality. Let’s work together to build a more inclusive and efficient financial landscape for all South Africans.
Frequently Asked Questions
What is the National Credit Act (NCA) and how does it affect digital lending?
The NCA is the primary legislation regulating the South African credit market to prevent reckless lending and ensure consumer protection. It mandates that every digital lending platform south africa must perform rigorous affordability assessments and provide transparent pre-agreement statements. Compliance ensures that lenders operate within interest rate caps and follow fair collection practices, protecting both the institution and the consumer from significant legal risk.
Can a digital lending platform integrate with South African credit bureaux?
Yes, modern platforms are designed to integrate seamlessly with major credit bureaux like TransUnion, Experian, and XDS via secure APIs. This capability allows for real-time data retrieval, enabling lenders to assess a borrower’s credit history and existing debt obligations instantly. Such integrations are vital for automating the vetting process and reducing the time-to-cash for applicants whilst maintaining a high standard of risk management.
How long does it take to develop a custom digital lending platform?
The development timeline for a bespoke platform typically ranges from four to nine months, depending on the complexity of the required features. A basic system with core management functions might launch sooner, whilst a platform requiring advanced AI automation and deep banking integrations takes longer to architect. We focus on a methodical execution that ensures each phase, from strategic consulting to cloud deployment, is handled with precision.
What is the difference between a P2P lending platform and an enterprise LMS?
A P2P platform acts as a marketplace matching individual lenders with borrowers, whereas an enterprise Loan Management System (LMS) is a comprehensive back-office solution for financial institutions. An LMS manages the entire loan lifecycle, including complex accounting, automated collections, and regulatory reporting. Whilst P2P tools focus on matching, an enterprise LMS provides the scalable digital infrastructure needed to manage a large, proprietary loan book securely.
Is cloud hosting for financial data legal in South Africa?
Cloud hosting is entirely legal and increasingly preferred, provided the infrastructure complies with POPIA and the South African Reserve Bank’s outsourcing guidelines. Data must be stored securely with advanced encryption, and lenders must ensure that their cloud provider meets specific residency and security standards. Using local data centres helps institutions meet these regulatory requirements whilst ensuring high platform performance and reliability for all users.
How does AI improve the loan approval process in South Africa?
AI enhances the approval process by analysing non-traditional data points to assess creditworthiness more accurately than traditional scoring alone. This is particularly effective for reaching the unbanked population who may lack a formal credit history. By automating risk assessment through a digital lending platform south africa, institutions can process thousands of applications simultaneously with greater precision, significantly reducing the likelihood of human error or subjective bias.
What security measures are required for a digital lending platform?
A platform must implement multi-layered security, including end-to-end encryption, multi-factor authentication (MFA), and rigorous access controls. Regular vulnerability assessments and penetration testing are essential to defend against evolving cyber threats. These measures protect sensitive borrower data and ensure that financial transactions remain secure, which is fundamental to maintaining the quiet confidence and reliability expected of a modern financial service provider in the national market.
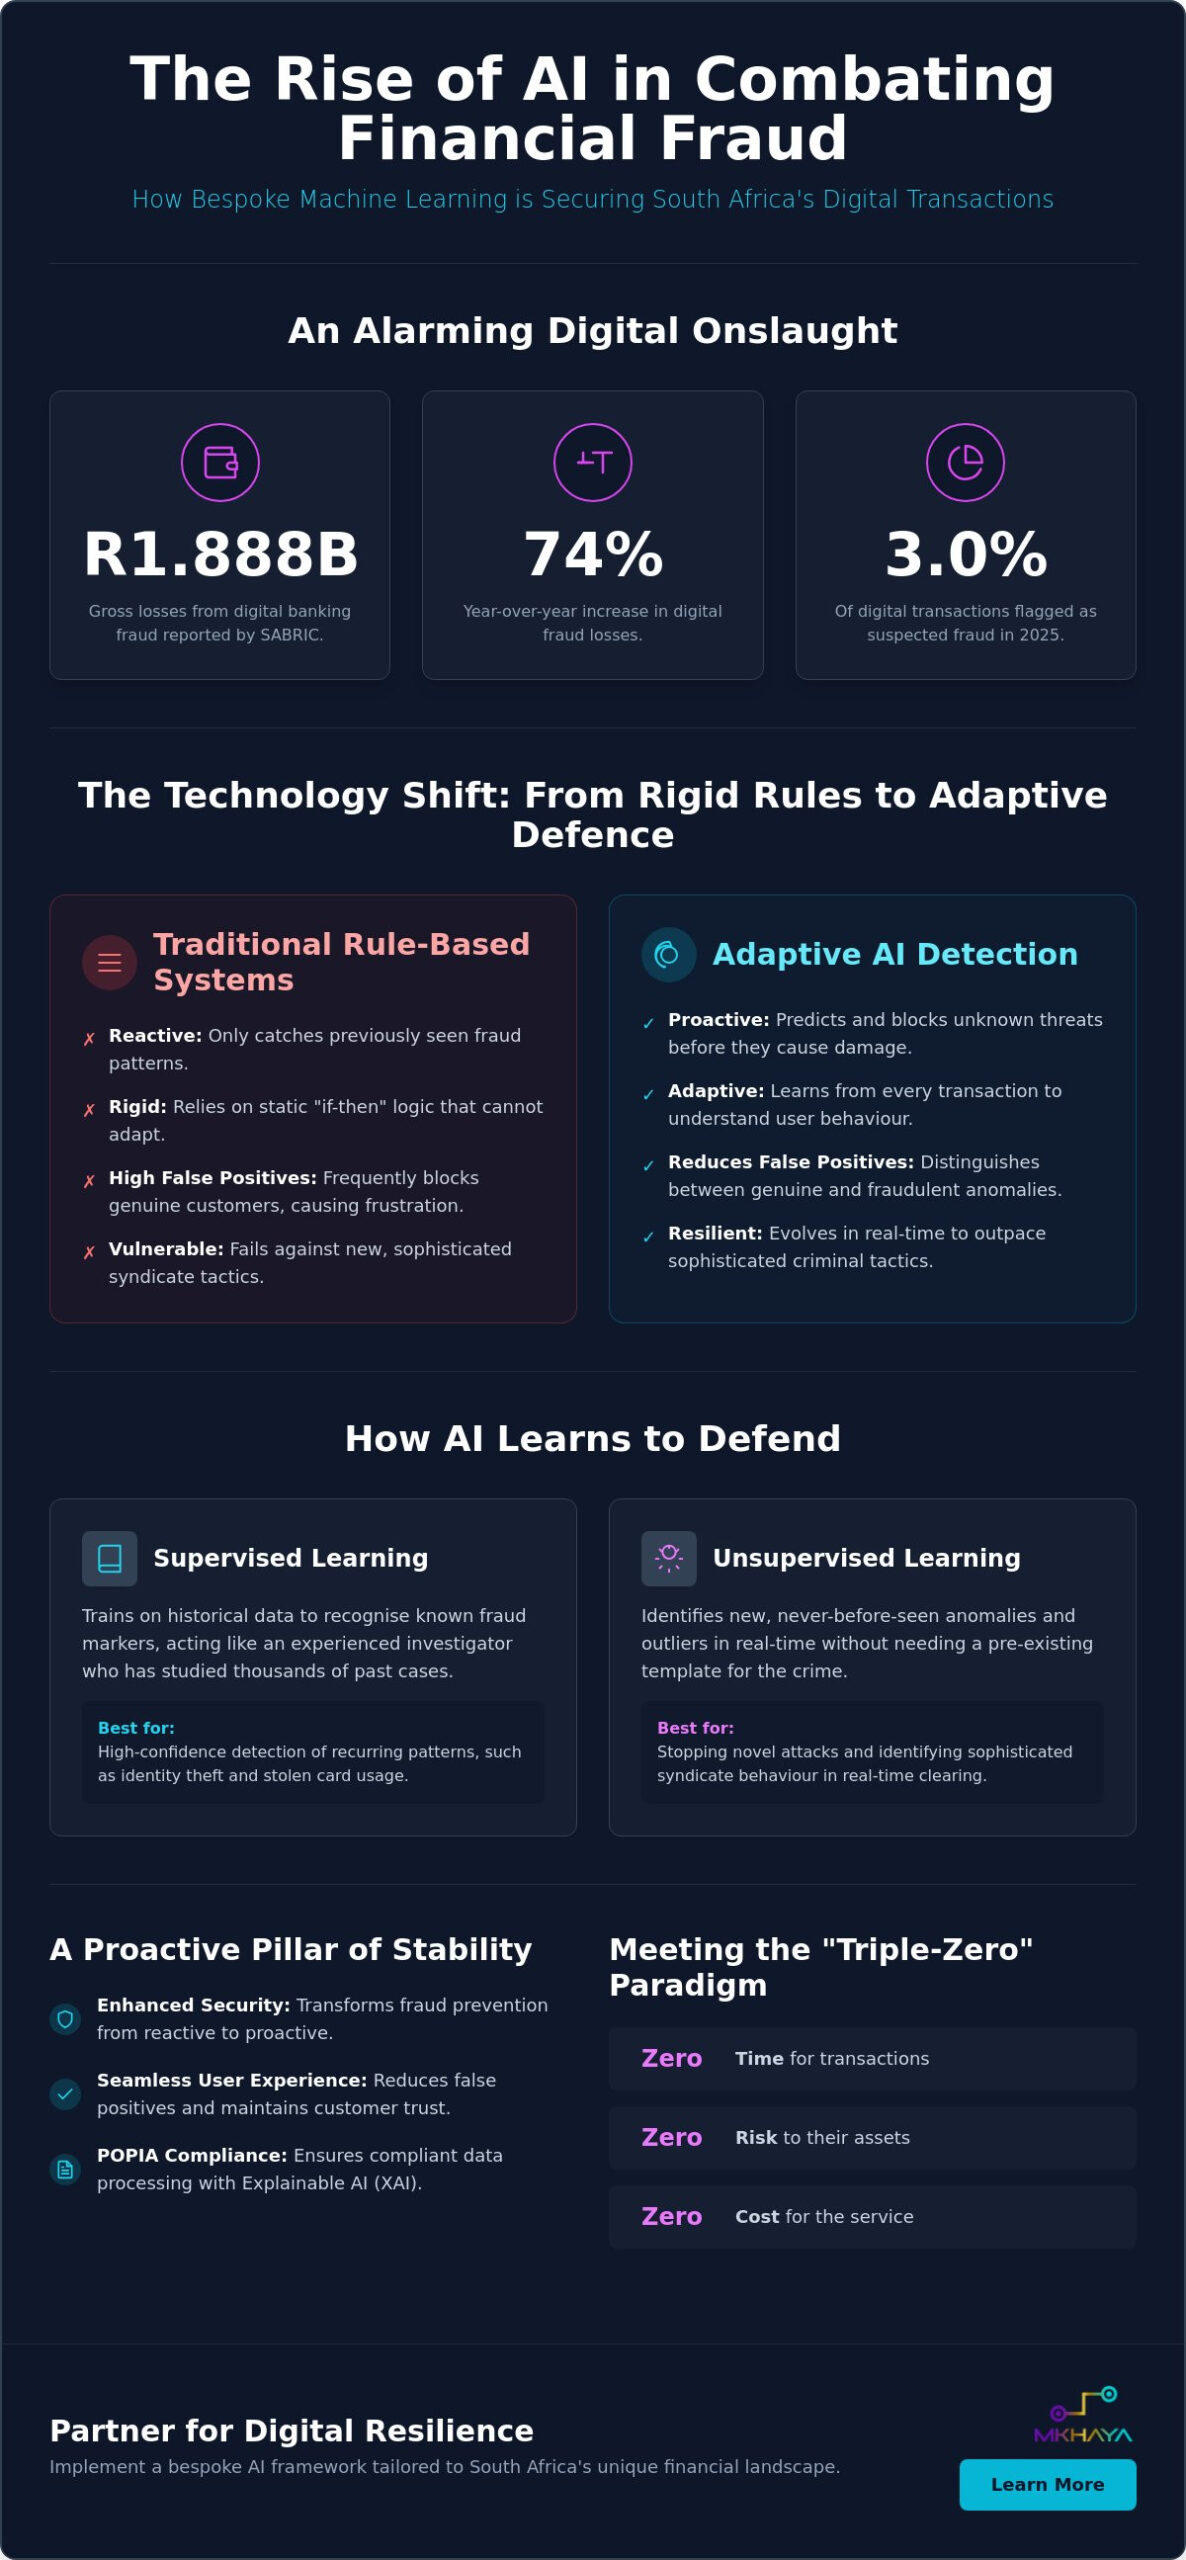
With 3.0% of all digital transactions in South Africa flagged as suspected fraud in 2025, our local financial sector faces a digital onslaught unlike any other on the continent. You’ve likely seen the reports from SABRIC showing gross losses from digital banking fraud reaching R1.888 billion, a staggering 74% year-over-year increase. It’s clear that relying on legacy systems for real-time clearing is no longer enough to protect your customers or your bottom line. Integrating bespoke AI for fraud detection in financial services South Africa has become a necessity for institutions that want to outpace sophisticated syndicates whilst maintaining a seamless user experience.
We understand the frustration of balancing rigorous security with the need to reduce false positives that alienate genuine clients. This case study discovers how South African institutions are leveraging custom AI and data automation to secure digital transactions and ensure compliant data processing under POPIA. You’ll learn how a strategic shift toward scalable, locally-tuned infrastructure can transform fraud prevention from a reactive cost centre into a proactive pillar of stability. We’ll examine the move from generic global models to precision-engineered solutions that handle the unique behavioural nuances of our domestic market.
Key Takeaways
Understand how adaptive machine learning models outpace rigid, rule-based systems to identify sophisticated local fraud patterns in real-time.
Evaluate the strategic advantages of building bespoke AI for fraud detection in financial services South Africa to ensure solutions are tailored to your specific transaction behaviours.
Master the architectural essentials of a fraud prevention engine, focusing on data aggregation and the engineering of unique local features.
Explore how specialised staff augmentation provides the expertise needed to bridge the technical skills gap and maintain digital resilience.
Discover a clear path toward reducing fraud losses and ensuring POPIA compliance without compromising the customer experience during high-volume clearing.
AI for fraud detection in financial services South Africa involves deploying machine learning algorithms that scrutinise millions of data points to identify and block fraudulent activities in real-time. In the broader context of Financial technology (FinTech), these systems act as the primary line of defence against a rising tide of sophisticated local threats. South African institutions currently navigate a complex environment where card-not-present fraud, identity theft, and the creation of synthetic identities are becoming increasingly common. With suspected digital fraud rates hitting 3.0% in 2025, the highest in Africa, the pressure to automate has never been greater.
The urgency for these systems is driven by what industry leaders call the “triple-zero” paradigm. Modern banking customers expect zero time for transactions, zero risk to their assets, and zero cost for the service. To meet these expectations whilst managing the high-volume requirements of real-time clearing, automated intervention is the only viable path. The South African Reserve Bank (SARB) and the Financial Sector Conduct Authority (FSCA) have set high security expectations. Specifically, the 2025 Joint Standard on Cybersecurity and Cyber Resilience makes robust AI integration a regulatory priority for any institution handling public funds.
The Shift from Reactive to Proactive Security
Traditional “if-then” rules are rigid; they only catch what has happened before. When fraud syndicates evolve their tactics, these legacy systems fail because they cannot adapt to new patterns without manual updates. The cost of remaining reactive is high. Beyond the R1.888 billion in gross losses reported by SABRIC, institutions face severe brand reputation damage that can take years to repair. Proactive AI detection marks the shift from merely stopping known threats to predicting unknown anomalies before they impact the customer.
Local Regulatory Compliance: POPIA and Beyond
Implementing AI requires a delicate balance between data-heavy training and strict adherence to the Protection of Personal Information Act (POPIA). Financial institutions must ensure that the data used to train models is handled with absolute integrity. This has led to the rise of “Explainable AI” (XAI). This approach allows banks to provide clear reasoning for why a transaction was flagged, which is essential for regulatory reporting and customer transparency. Leveraging expert digital transformation services helps organisations align their technical infrastructure with these complex compliance mandates whilst maintaining operational agility.
How AI-Driven Detection Surpasses Traditional Systems
Traditional fraud prevention relies on rigid, rule-based logic that operates on “if-then” scenarios. For example, a system might be programmed to flag any transaction over R10,000 or any purchase made outside of a user’s home province. Whilst these rules provided a basic safety net in the past, they’re often too blunt for modern requirements. They result in high rates of false positives, where genuine customers find their accounts frozen during legitimate activities. In contrast, AI for fraud detection in financial services South Africa utilises fluid, adaptive models that learn from every interaction, allowing for a far more nuanced understanding of what constitutes a threat.
These advanced systems typically employ a hybrid approach, combining supervised and unsupervised learning to create a multi-layered defence. Supervised learning acts like an experienced investigator who has studied thousands of past fraud cases. By training on historical data, these models recognise specific markers associated with known crimes, such as stolen card patterns or phishing signatures. However, because fraud syndicates constantly pivot, relying solely on history isn’t enough. This is where unsupervised learning becomes vital. These algorithms identify outliers in transaction behaviour that have never been seen before, flagging suspicious account-to-account transfers in real-time clearing environments without needing a prior “template” of the crime.
Supervised vs Unsupervised Machine Learning
The choice between these methods depends on the specific threat. Supervised ML is excellent for high-confidence detection of recurring patterns, such as identity theft attempts during loan applications. Unsupervised ML excels at spotting “zero-day” fraud, particularly amongst the high-velocity transactions seen in digital banking. Modern engines also incorporate deep learning to analyse unstructured data, such as customer support transcripts or login metadata, to detect subtle signs of account takeover. Navigating the challenges of AI in fraud detection requires this balanced, sophisticated architecture to ensure no stone is left unturned.
Reducing False Positives: The Customer Experience Factor
Precision is the ultimate goal for any financial institution. AI distinguishes between a traveller using their card in a new city and a fraudster attempting a remote transaction by analysing hundreds of variables, from device biometrics to the time of day. This precision reduces “friction,” ensuring that genuine transactions succeed on the first attempt. When you lower the number of blocked legitimate payments, you directly improve customer loyalty and retention. If you’re ready to move beyond rigid rules, exploring bespoke AI and data automation solutions can help you build a system that protects your revenue whilst respecting your customers’ time.
Implementing Bespoke AI Frameworks: A Practical Comparison
When choosing a framework for AI for fraud detection in financial services South Africa, the “buy versus build” debate is often the first hurdle for stakeholders. Off-the-shelf SaaS tools offer a quick start, but they frequently lack the granular control needed for our local market. Bespoke solutions, built on a foundation of custom software engineering, provide the flexibility to adapt to unique South African transaction patterns whilst ensuring total data sovereignty. This is particularly relevant given the strict requirements of POPIA; keeping sensitive financial data within local borders isn’t just a preference, it’s a regulatory necessity for many organisations today.
Off-the-Shelf vs Bespoke AI Solutions
Generic fraud models are often trained on European or North American datasets. These models frequently struggle with the nuances of the South African “informal economy” where transaction behaviours may appear irregular to a global algorithm but are perfectly normal locally. When you choose a bespoke framework for AI for fraud detection in financial services South Africa, you gain the ability to customise detection logic to these specific domestic realities. Beyond customisation, the long-term ROI of owning your intellectual property (IP) is substantial. You aren’t just renting a service; you’re building a proprietary asset that grows in value as it learns from your specific data pool. Local support also means your partner understands the immediate context of a new fraud wave hitting Cape Town or Johannesburg, allowing for faster model retraining. For a broader strategic perspective on reducing operational overheads through intelligent automation, the AI automation solutions South Africa executive guide for 2026 provides a comprehensive roadmap for enterprises navigating these decisions.
Real-Time Data Processing and Cloud Infrastructure
The shift toward Real-Time Clearing (RTC) in South Africa has changed the technical requirements for fraud prevention. It’s no longer acceptable to flag a transaction after the money has left the account. Your AI must process data with sub-second latency to block fraudulent transfers before they are finalised. Achieving this level of performance requires more than just a smart algorithm; it demands a robust backend. Leveraging managed cloud services allows your infrastructure to scale instantly during massive data spikes, such as month-end salary runs or Black Friday sales. By integrating these AI models into your existing ERP and banking cores through microservices, you create a seamless flow of information that supports both security and speed. This architectural precision ensures that your digital resilience remains stable even as transaction volumes grow, preventing legacy system bottlenecks from frustrating your genuine customers.
Case Study: Architecting an AI-Powered Fraud Prevention Engine
Building a resilient system for AI for fraud detection in financial services South Africa requires a structured, methodical approach that moves beyond simple software installation. It’s about creating a living architecture that evolves alongside the tactics of local syndicates. A successful implementation follows five critical steps to ensure the engine is both accurate and scalable within the South African banking context.
Step 1: Data Aggregation — We begin by centralising siloed data from across the institution, breaking down the walls between credit card history, personal loan applications, and savings account metadata.
Step 2: Feature Engineering — Our team identifies local variables that predict fraud, such as unusual high-value EFT patterns during public holidays or branch-specific anomalies that global models often overlook.
Step 3: Model Training and Testing — We refine the engine’s accuracy by using historical South African fraud data, ensuring the system recognises the specific signatures of regional threats.
Step 4: Deployment and Monitoring — The model is transitioned into the live transaction stream where it begins continuous learning in a real-world environment.
Step 5: Feedback Loops — Human analyst insights are integrated back into the model; this ensures that “grey area” cases are correctly categorised to improve future performance.
Phase 1: Discovery and Data Strategy
Auditing existing data quality is the first hurdle in any strategic build. We look for “dark data,” such as failed login attempts or specific device metadata, which often contains hidden patterns of account takeover behaviour. During this phase, we set clear KPIs that balance aggressive fraud detection rates with acceptable false positive thresholds to protect the customer experience. Following the structured Mkhaya MK process ensures that this discovery phase is thorough and sets a stable foundation for the technical work that follows.
Phase 2: Building the Neural Network
A successful build requires a balanced team of data scientists and specialised software engineers working in tandem. We place a heavy emphasis on “Adversarial AI,” where we train the system by simulating sophisticated fraud attacks based on known local syndicate behaviours. This stress-testing ensures the neural network is prepared for the unexpected. Predictive analytics can identify the precursor signs of an account takeover and stop the fraud before the final transaction is even initiated. This proactive stance is what separates modern digital banking from legacy reactive security measures.
If you’re ready to secure your infrastructure against evolving threats, our team provides the AI and data automation expertise needed to build a precision-engineered fraud engine.
Partnering for Digital Resilience: The Mkhaya MK Approach
Effective implementation of AI for fraud detection in financial services South Africa requires a partner who balances visionary strategy with practical, boots-on-the-ground execution. At Mkhaya MK, we position ourselves as more than just a service provider; we act as a steady anchor for institutions navigating the rapid shifts in the technological landscape. Our approach focuses on mutual success, ensuring that every custom algorithm or neural network we build serves a clear business outcome. We move from high-level conceptualisation to methodical deployment, creating a sense of momentum that leads your institution toward a more secure digital future.
One of the most significant hurdles in our local market is the scarcity of specialised talent. We address this directly through staff augmentation, providing the high-end expertise your projects require without the delays of traditional recruitment. This model allows you to scale your technical capabilities instantly, bringing in data scientists and engineers who understand the unique nuances of the South African financial sector. Security shouldn’t exist in a vacuum. By integrating these advanced AI models with your broader ERP solutions, we create a holistic security environment where fraud detection data informs every facet of your business operations.
Extending Your Internal Tech Team
We believe in the power of collaborative growth. When we provide specialised talent for your machine learning projects, our focus remains on long-term stability and reliability. Whether through on-site or remote engagement, our experts work alongside your staff to ensure a seamless knowledge transfer. This ensures that your internal team possesses the skills and confidence to manage and refine the AI for fraud detection in financial services South Africa once the initial deployment is complete. It’s a supportive partnership designed to build your internal resilience rather than creating a cycle of dependency.
The Future of AI in South African Finance
As we look toward 2027, the horizon of fraud prevention continues to expand. We anticipate a significant shift toward biometric integration and blockchain-based verification systems that offer even greater layers of protection. Digital transformation isn’t a destination with a fixed end point; it’s a continuous journey of refinement and construction. Staying ahead of sophisticated syndicates requires an agile mindset and a commitment to constant evolution. If you’re ready to define your path forward, we invite you to consult with Mkhaya MK on your AI roadmap and secure your position as a leader in digital banking.
Securing Your Financial Future Through Precise Innovation
Building a resilient defence against modern fraud syndicates is no longer just a technical requirement; it’s a strategic pillar for long-term stability. You’ve seen how shifting from rigid rules to adaptive machine learning allows for real-time protection whilst respecting the customer experience. By choosing bespoke AI for fraud detection in financial services South Africa, your institution gains a system that understands the nuances of our local informal economy and the high-velocity demands of real-time clearing. This transition ensures that your security infrastructure remains as agile and forward-thinking as the clients you serve.
The journey toward digital resilience is one we’re ready to walk with you. Whether you need end-to-end custom software engineering, specialised expertise through our national staff augmentation service, or advanced AI and data automation, we provide the methodical execution your vision requires. It’s time to transform your security from a reactive cost centre into a proactive engine of growth and trust. Partner with Mkhaya MK for your AI and Digital Transformation journey and let’s build a secure, stable future for your institution together.
Frequently Asked Questions
How does AI detect fraud in real-time for South African banks?
AI systems analyse millions of data points instantly by comparing current transaction behaviour against both historical patterns and emerging anomalies. In the South African banking sector, this capability is essential for Real-Time Clearing (RTC), as it allows the engine to flag and block suspicious EFTs or card-not-present transactions before the funds leave the account. This immediate intervention prevents losses that legacy systems would only identify hours after the event.
Can AI fraud detection help with POPIA compliance?
Yes, modern AI frameworks are designed with privacy-by-design principles that align with the Protection of Personal Information Act (POPIA). By utilising “Explainable AI” (XAI), financial institutions can generate clear audit trails that justify why a transaction was flagged whilst ensuring that personal data is processed securely and for a specific purpose. This transparency is vital for meeting the security expectations set by the FSCA and SARB.
What is the difference between rules-based and AI fraud detection?
Rules-based systems rely on static “if-then” logic that only catches known threats, often leading to high rates of false positives. AI for fraud detection in financial services South Africa is adaptive; it uses machine learning to learn from every interaction and identify unknown anomalies. This fluid approach allows the system to evolve alongside local syndicates, catching sophisticated tactics that fixed rules would simply overlook.
Is bespoke AI fraud software better than off-the-shelf solutions for SA businesses?
Bespoke solutions offer a significant advantage because they are trained on domestic datasets that reflect South African transaction behaviours and the nuances of our informal economy. Generic off-the-shelf tools often struggle with these local patterns, leading to unnecessary friction for genuine customers. A custom-built engine also ensures total data sovereignty, keeping sensitive financial information within local borders as required by many regulatory frameworks.
How long does it take to implement an AI fraud detection system?
A typical implementation follows a phased journey that usually spans several months. This timeline includes an initial discovery and data strategy phase, followed by data aggregation, feature engineering, and rigorous model testing. We focus on a methodical execution to ensure the system is stable and reliable before it begins monitoring live transaction streams, ensuring a smooth transition for your internal teams.
What data is required to train an AI fraud detection model?
Training requires a robust pool of historical transaction records, customer metadata, and documented fraud signatures from previous incidents. We also look for “dark data,” such as failed login attempts and device biometrics, to provide the context needed for detecting account takeovers. The more diverse and locally relevant the data, the more precise the AI for fraud detection in financial services South Africa becomes at predicting future threats.
How do you reduce false positives in AI-driven fraud prevention?
False positives are reduced by refining the model to distinguish between legitimate behavioural shifts, such as a customer travelling, and actual fraudulent intent. By scrutinising hundreds of variables simultaneously, the AI gains a precise understanding of the user’s typical behaviour. This cause-and-effect relationship ensures that you lower the “friction” for genuine clients whilst maintaining a high-security threshold for suspicious activities.
Do I need a dedicated data science team to run AI fraud detection?
You don’t need to hire a permanent, full-scale team before you begin your journey. Many institutions use bespoke AI automation solutions in South Africa to bring in specialised experts who build the initial architecture and deploy the models. This collaborative approach ensures a thorough knowledge transfer, allowing your existing IT staff to gain the skills needed to manage and maintain the AI engine post-deployment with confidence.