Digital Lending Platform South Africa: The 2026 Strategic Guide
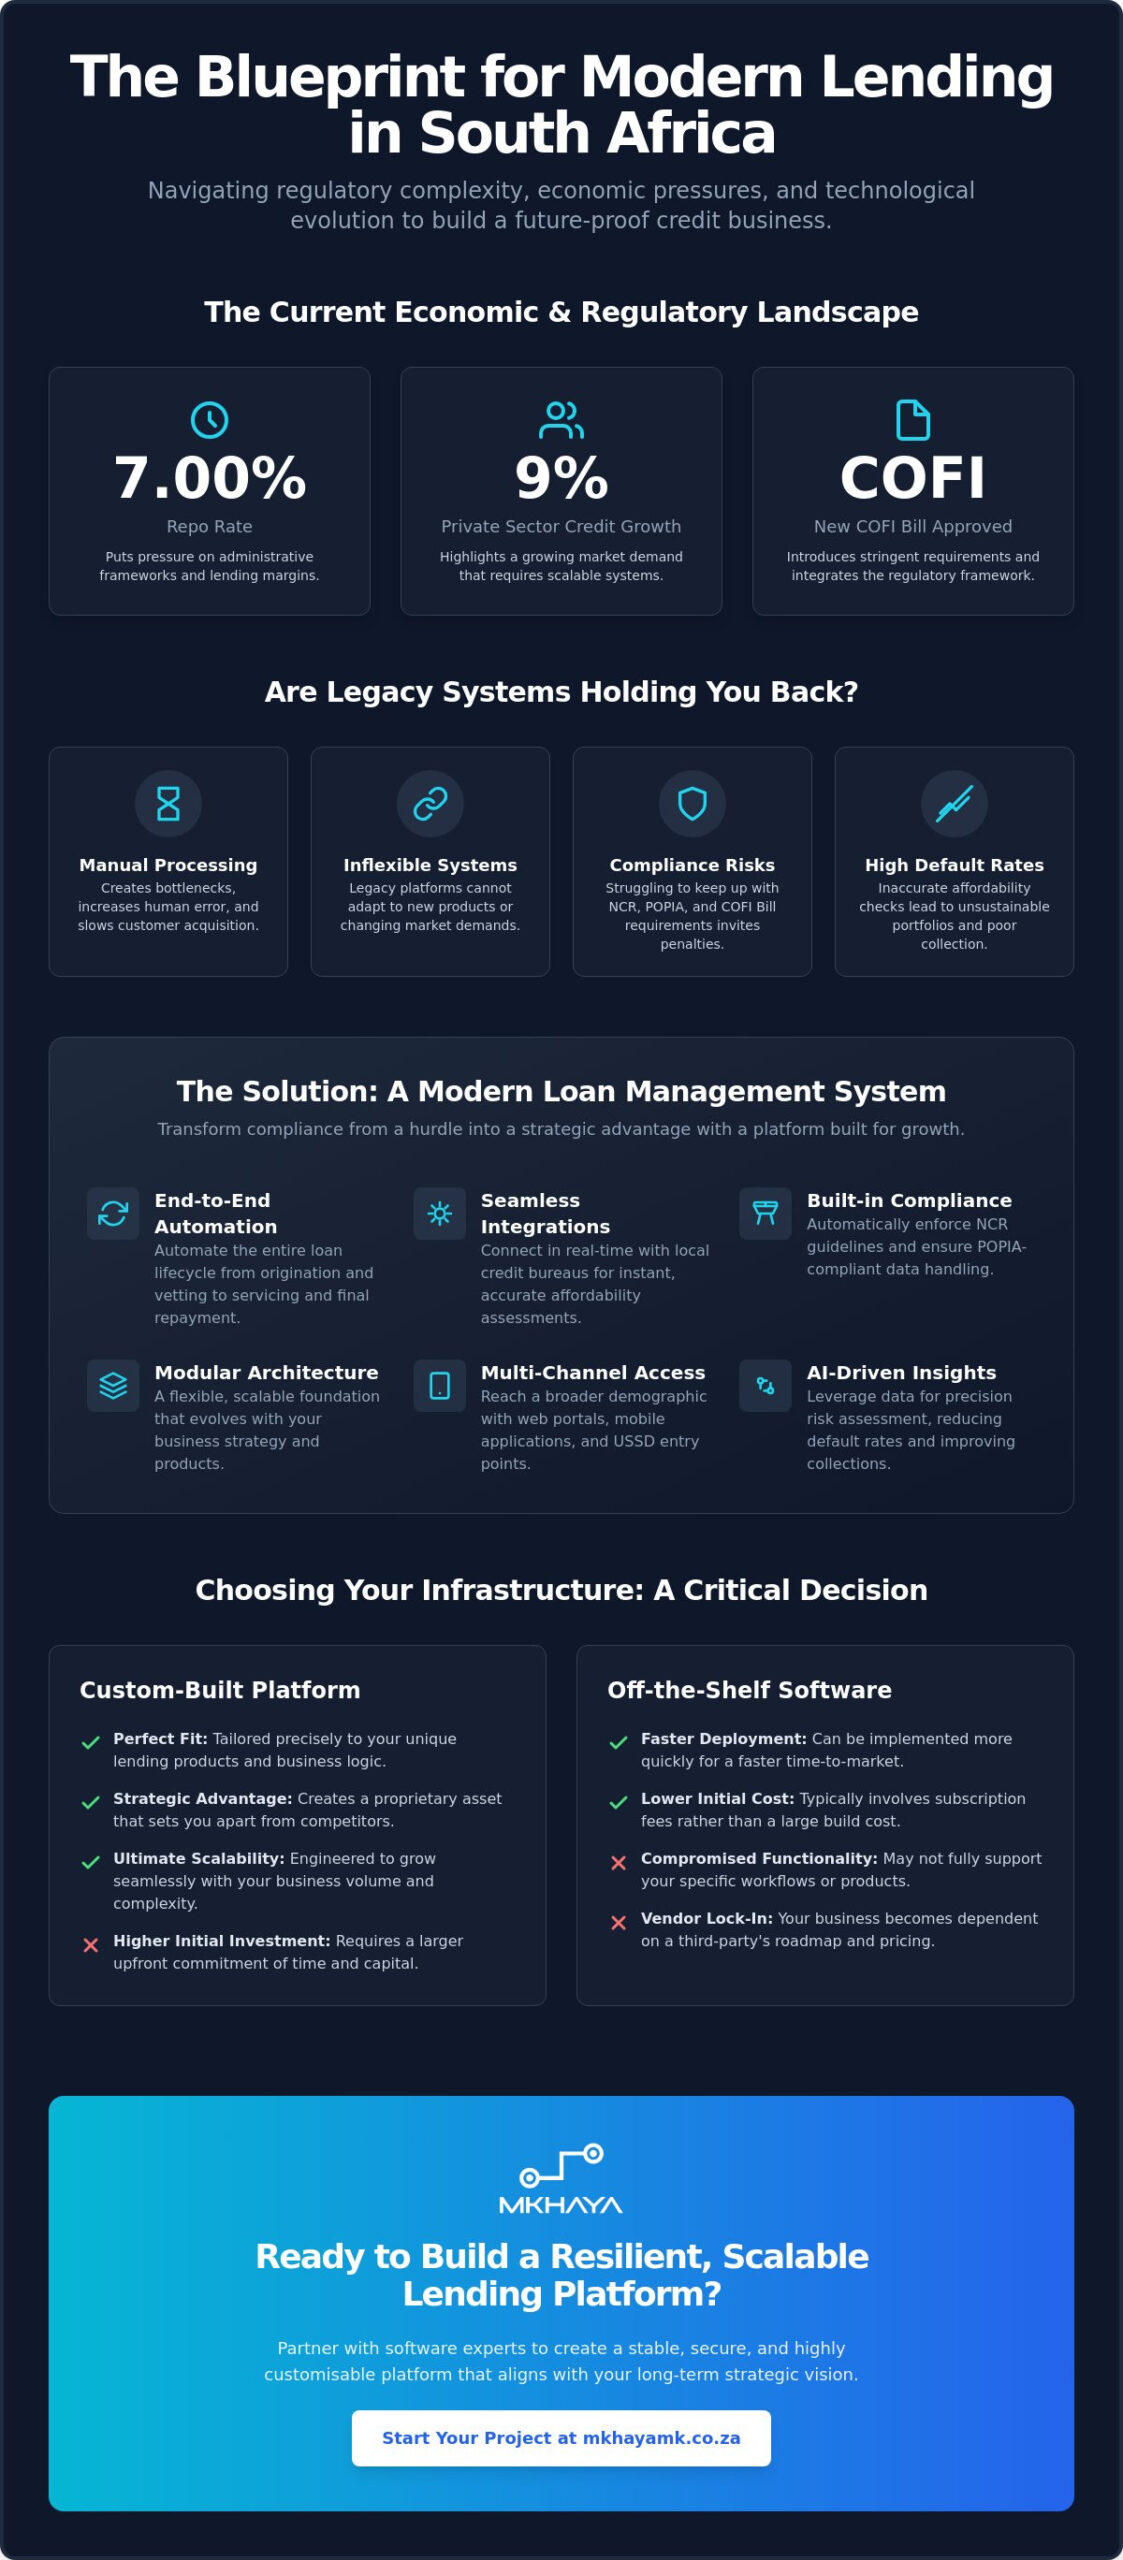
With South Africa’s digital lending and fintech market value reaching USD 980 million in 2026, the opportunity for growth is immense, yet many providers remain tethered to the past. Even with the repo rate holding steady at 7.00%, the pressure to maintain margins whilst managing manual, paper-heavy credit approvals is becoming unsustainable. If you’re struggling to balance high operational costs with the complexities of NCR and POPIA compliance, you’ve likely felt the need for a more agile approach. Implementing a robust digital lending platform south africa requires more than just a technical upgrade; it’s about building a strategic engine that can navigate our unique credit landscape.
We believe that scaling a financial service should be a collaborative journey rooted in reliability and precision. This strategic guide will show you how to modernise your credit operations and scale using cutting-edge technology designed for the local market. You’ll learn how to achieve faster loan processing times through automated risk assessment and establish a scalable digital infrastructure that ensures long-term stability. We will walk through the essential steps to move from a broad vision to concrete execution, ensuring your business remains a stable anchor in a rapidly changing technological environment.
Key Takeaways
- Understand how modernising your credit operations through cloud-native architectures facilitates sustainable growth and reduces operational overhead.
- Identify the core features of a modern digital lending platform south africa, focusing on how AI-driven scoring and secure disbursements accelerate turnaround times.
- Evaluate the strategic advantages of custom software development to protect your proprietary IP and avoid the limitations of generic lending tools.
- Navigate the latest NCR and POPIA requirements with precision to ensure your digital infrastructure remains secure and compliant in 2026.
- Explore a structured path from strategic consulting to cloud deployment, positioning your financial services as a stable anchor in a changing market.
What is a Digital Lending Platform and Why Does it Matter in 2026?
Understanding What is a Digital Lending Platform starts with recognising it as an end-to-end software solution that automates the entire loan lifecycle. In 2026, these systems have evolved far beyond basic data entry tools. They now function as sophisticated engines that manage everything from initial customer onboarding and credit vetting to disbursement and collections. For any financial institution, a digital lending platform south africa is the cornerstone of a modernised service, replacing slow, fragmented legacy systems with a unified, cloud-native architecture.
To better understand how these tools are reshaping the local market, watch this helpful video:
The transition from legacy credit systems to AI-driven architectures is fueled by a need for absolute precision and speed. Traditional methods often result in bottlenecks that frustrate borrowers and increase risk for lenders. Modern platforms utilise AI & data automation to ingest vast amounts of data instantly, ensuring that credit decisions are based on real-time insights rather than outdated snapshots. This shift allows lenders to remain agile whilst maintaining a high standard of reliability.
South African businesses are currently prioritising digital transformation to drastically reduce “time-to-cash”. In a competitive market, the ability to put capital into a borrower’s hands within minutes rather than days is a significant advantage. Mobile-first interfaces play a vital role here, especially in reaching the unbanked and underbanked national population. By providing access to financial services through the devices people already carry, these platforms foster greater financial inclusion across the country.
The Evolution of Credit in South Africa
Credit management has moved from manual, subjective vetting to real-time algorithmic risk assessment. This evolution relies on robust cloud application services to ensure maximum platform uptime and accessibility. By removing physical barriers and geographical constraints, digital platforms democratise access to capital. This means an entrepreneur in a remote area can secure funding with the same ease and speed as a business based in a major urban centre like Johannesburg or Cape Town.
Core Benefits for Financial Institutions
Adopting automated workflows leads to a substantial reduction in operational overheads. By removing the need for manual intervention at every stage, institutions can process significantly higher loan volumes without a linear increase in staff costs. Precision also improves; algorithmic scoring reduces the human error inherent in traditional vetting, leading to a healthier loan book. For South African SMEs, the ROI of a Loan Management System is found in the ability to secure working capital at the exact moment of opportunity, turning credit into a catalyst for immediate and sustainable expansion.
Essential Features of a Modern Digital Lending Platform
Selecting the right components for your digital lending platform south africa is a strategic decision that determines your long-term scalability. Whilst many off-the-shelf products offer basic functionality, a truly robust system must handle the specific nuances of the local credit market. You need a platform that doesn’t just record data but actively works to protect your margins and improve the user journey. These core capabilities form the foundation of a reliable system:
- Automated Credit Scoring: Integrating AI and data automation to process applications in seconds rather than days.
- Secure Digital Wallets: Facilitating seamless disbursements and repayments through integrated payment gateways.
- Interactive Dashboards: Providing real-time analytics for lenders to monitor portfolio health and for borrowers to manage their accounts.
- Multi-Channel Support: Ensuring accessibility via web, mobile, and USSD to reach the widest possible national audience.
AI-Driven Risk Assessment and Automation
Incorporating AI automation solutions allows your platform to predict default patterns with far greater precision than traditional credit scores. This isn’t just about speed; it’s about accuracy. By automating KYC (Know Your Customer) and AML (Anti-Money Laundering) checks, you reduce manual friction whilst ensuring rigorous compliance. We’ve found that custom-built algorithms often outperform generic global models. Localised data reflects South African spending habits and financial behaviours more accurately, which leads to a more stable and predictable loan book.
User Experience and Interface Design
Borrower retention is heavily influenced by the ease of the initial digital journey. Professional UI/UX design services are critical for simplifying complex application forms into intuitive, bite-sized steps. In the South African context, high performance on low-bandwidth mobile connections is a non-negotiable requirement. A platform that fails to load on a basic smartphone in a rural area isn’t truly accessible. By focusing on lightweight yet powerful interfaces, you ensure that your service remains available to everyone, regardless of their device or location.
If you’re looking to refine these features for your specific business model, our team can help you customise your lending infrastructure for long-term success. We believe that technology should be a supportive partner in your growth, providing the steady confidence you need to scale your financial services with precision.
Custom Development vs. Off-the-Shelf Lending Software
Deciding whether to build a bespoke solution or license a generic product is a pivotal moment for your business strategy. Whilst off-the-shelf software offers a faster entry point, it often introduces the risk of “vendor lock-in”, where your growth is constrained by another company’s roadmap. For a digital lending platform south africa, owning your proprietary IP isn’t just a technical preference; it’s a significant asset that increases the valuation of your financial institution. Custom engineering allows you to architect unique credit products that align perfectly with local market needs, such as specific repayment structures or interest rate tiers that generic SaaS tools simply cannot accommodate.
We believe that technology should serve your vision, not limit it. Choosing custom software development enables you to build a system that reflects your specific risk appetite and operational style. Whilst the initial capital expenditure for custom builds is higher than a monthly subscription, the long-term operational savings are substantial. You eliminate recurring per-user fees and gain the freedom to scale without penalty, turning your technology stack into a stable anchor for future expansion.
When to Choose a Custom Solution
Bespoke development is the right path when your product requirements involve complexities that standard tools ignore. If you need deep, seamless integration with local credit bureaux like Experian or TransUnion, or direct links into the South African banking grid, a custom approach is often essential. This path is also vital if you aim to build a unique brand experience that stands out amongst a sea of generic competitors. A custom-built Loan Management System ensures that every touchpoint, from the application to the final repayment, feels modern and precise.
The Role of Staff Augmentation in Development
Bridging the local developer talent gap is one of the biggest challenges in fintech today. Many institutions find that staff augmentation provides the necessary momentum to meet aggressive launch deadlines without the overhead of permanent hiring. By integrating dedicated software engineering experts into your existing team, you ensure project continuity and maintain high standards of precision. This model allows you to scale your technical capacity quickly, bringing in specialised skills for cloud deployment or AI integration exactly when they’re needed most. It’s a practical way to maintain the “quiet confidence” required to execute a complex digital transformation whilst keeping your core focus on financial service delivery.
Navigating Compliance and Security in South Africa
Operating a digital lending platform south africa involves more than just processing applications; it requires a deep commitment to the regulatory frameworks that protect both the lender and the borrower. In 2026, the South African Reserve Bank and the National Credit Regulator (NCR) have set high standards for digital transparency. Reliability in this sector is built on a foundation of methodical execution and strict adherence to the National Credit Act. By integrating compliance directly into your software architecture, you transform a potential hurdle into a competitive advantage that inspires trust.
Manual reporting is often the primary cause of friction in growing financial institutions. A modern platform should automate the generation of Form 39 and Form 40 reports, ensuring that your data is always ready for submission. Managing reckless lending checks within the digital workflow is equally critical. By using algorithmic affordability assessments, you can ensure every loan meets the legal requirements for consumer protection whilst maintaining your operational speed. Integrating with the South African Fraud Prevention Service (SAFPS) adds an extra layer of security, allowing you to flag suspicious activity before it impacts your bottom line.
NCR and National Credit Act Compliance
With the Conduct of Financial Institutions (COFI) Bill now creating a unified framework for open finance, your platform must be agile enough to adapt to these shifting rules. Ensuring your interest rate calculations remain within the National Credit Act caps, such as the 5% per month limit for short-term consumer loans, must be an automated function of your core system. This precision prevents accidental overcharging and protects your organisation from regulatory scrutiny. Automated workflows also ensure that every borrower receives the required pre-agreement statements and quotations, honouring the transparency standards expected in a modern financial market.
Data Privacy and POPIA
Protecting your infrastructure requires more than basic firewalls. Utilising robust cloud solutions provides the high-end security and encryption needed to defend against sophisticated cyber threats. Data privacy is a cornerstone of modern financial services, and implementing POPIA-compliant protocols ensures that borrower information is handled with the precision it deserves. This includes securing data with advanced encryption and managing strict access controls so that only authorised personnel can view sensitive files. Your platform must also provide clear mechanisms for managing consent and data subject rights, allowing borrowers to see exactly how their information is used. Non-compliance in the South African financial sector can result in administrative fines of up to R10 million or criminal prosecution for significant data breaches.
If you’re ready to build a compliant and secure future for your business, we invite you to speak with our compliance engineering team today.
How Mkhaya MK Modernises Lending with Custom Engineering
At Mkhaya MK, we understand that a digital lending platform south africa is more than just code; it is the lifeblood of your financial service. Our proprietary Loan Management System serves as a robust foundation, designed specifically to handle the intricacies of the local market whilst providing the flexibility to scale. We don’t just provide a tool; we embark on a collaborative journey with you, moving methodically from strategic consulting through to complex cloud deployment. This end-to-end process ensures that every architectural decision aligns with your long-term business goals and operational needs.
By leveraging AI & data automation, we help you create smarter credit operations that learn and adapt to borrower behaviour. This precision-focused approach reduces human error and enhances the reliability of your risk assessments. We believe in a partnership model where your success is our primary metric, providing a stable anchor in a technological landscape that never stops moving. Our goal is to inspire trust through transparency and methodical execution, ensuring your platform remains a visionary leader in the fintech space.
Bespoke Software Engineering for Fintechs
Designing scalable architectures is at the heart of our service offering. As your loan book grows, your infrastructure must remain agile and responsive to avoid the bottlenecks associated with legacy systems. Our software engineering teams focus on integrating your platform with local payment gateways and the broader financial ecosystem, ensuring seamless transactions for your customers. Our digital transformation methodology is built on commitment and integrity, allowing us to refine your processes whilst building for future innovation without the constraints of generic software.
Partnering for National Success
Success in the South African fintech space requires access to high-level expertise that can be difficult to source locally. Our staff augmentation model allows you to tap into top-tier technical professionals who become a dedicated extension of your own team. This approach ensures you have the talent needed to maintain your digital lending platform south africa at the cutting edge of the industry. We provide continuous support and optimisation, ensuring your system remains secure and efficient long after the initial launch. Take the next step toward modernising your credit operations; we invite you to consult with our engineering experts today to discover how we can build a more stable and successful future together.
Building the Future of South African Credit
Transitioning to a modernised credit operation is a strategic move that requires both vision and precision. We’ve explored how a digital lending platform south africa can transform manual bottlenecks into automated engines of growth, whilst ensuring your business remains compliant with NCR and POPIA regulations. By choosing custom engineering over generic software, you secure your proprietary IP and build a system that truly reflects your unique brand identity. Success in 2026 isn’t just about fast processing; it’s about creating a stable, scalable foundation that inspires long-term trust amongst your borrowers.
Our team is ready to support your journey with our specialised Loan Management System (LMS) and deep expertise in South African financial compliance. We combine scalable AI and cloud engineering capabilities to ensure your infrastructure is as agile as the market demands. We invite you to discuss your digital lending vision with Mkhaya MK and discover how a dedicated partnership can turn your strategic goals into a concrete reality. Let’s work together to build a more inclusive and efficient financial landscape for all South Africans.
Frequently Asked Questions
What is the National Credit Act (NCA) and how does it affect digital lending?
The NCA is the primary legislation regulating the South African credit market to prevent reckless lending and ensure consumer protection. It mandates that every digital lending platform south africa must perform rigorous affordability assessments and provide transparent pre-agreement statements. Compliance ensures that lenders operate within interest rate caps and follow fair collection practices, protecting both the institution and the consumer from significant legal risk.
Can a digital lending platform integrate with South African credit bureaux?
Yes, modern platforms are designed to integrate seamlessly with major credit bureaux like TransUnion, Experian, and XDS via secure APIs. This capability allows for real-time data retrieval, enabling lenders to assess a borrower’s credit history and existing debt obligations instantly. Such integrations are vital for automating the vetting process and reducing the time-to-cash for applicants whilst maintaining a high standard of risk management.
How long does it take to develop a custom digital lending platform?
The development timeline for a bespoke platform typically ranges from four to nine months, depending on the complexity of the required features. A basic system with core management functions might launch sooner, whilst a platform requiring advanced AI automation and deep banking integrations takes longer to architect. We focus on a methodical execution that ensures each phase, from strategic consulting to cloud deployment, is handled with precision.
What is the difference between a P2P lending platform and an enterprise LMS?
A P2P platform acts as a marketplace matching individual lenders with borrowers, whereas an enterprise Loan Management System (LMS) is a comprehensive back-office solution for financial institutions. An LMS manages the entire loan lifecycle, including complex accounting, automated collections, and regulatory reporting. Whilst P2P tools focus on matching, an enterprise LMS provides the scalable digital infrastructure needed to manage a large, proprietary loan book securely.
Is cloud hosting for financial data legal in South Africa?
Cloud hosting is entirely legal and increasingly preferred, provided the infrastructure complies with POPIA and the South African Reserve Bank’s outsourcing guidelines. Data must be stored securely with advanced encryption, and lenders must ensure that their cloud provider meets specific residency and security standards. Using local data centres helps institutions meet these regulatory requirements whilst ensuring high platform performance and reliability for all users.
How does AI improve the loan approval process in South Africa?
AI enhances the approval process by analysing non-traditional data points to assess creditworthiness more accurately than traditional scoring alone. This is particularly effective for reaching the unbanked population who may lack a formal credit history. By automating risk assessment through a digital lending platform south africa, institutions can process thousands of applications simultaneously with greater precision, significantly reducing the likelihood of human error or subjective bias.
What security measures are required for a digital lending platform?
A platform must implement multi-layered security, including end-to-end encryption, multi-factor authentication (MFA), and rigorous access controls. Regular vulnerability assessments and penetration testing are essential to defend against evolving cyber threats. These measures protect sensitive borrower data and ensure that financial transactions remain secure, which is fundamental to maintaining the quiet confidence and reliability expected of a modern financial service provider in the national market.